- Home
- Media Kit
- MediaJet
- Current Issue
- Past Issues
- Ad Specs-Submission
- Reprints (PDF)
- Photo Specifications (PDF)
- Contact Us
- PRIVACY POLICY
- TERMS OF USE
Loading
ONLINE
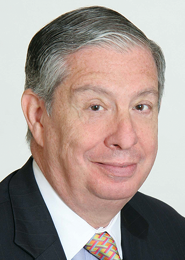
James W. Crystal
A Premium For Service
Editors’ Note
After joining his father, Frank Crystal, at Crystal & Company in 1961, James Crystal was named President in 1963. Crystal serves as Vice Chairman and Member of the Board of Alliant Insurance Services. He is also Vice Chairman, Trustee, and Member of the Executive and Finance Committees and Co-Chairman of the Audit Committee of Mount Sinai Health System, along with serving on the board of Congregation Emanuel.
Company Brief
Alliant Insurance Services (alliant.com) is one of the nation’s leading distributors of diversified insurance products and services. Operating through a national network of offices, Alliant offers a comprehensive portfolio of services to clients.
Historically, and as a young man starting in the business, what significant changes have evolved over the years and how have the concerns of businesses and personal lines clients changed?
Historically, the business has evolved significantly over the number of years that I have been involved. Perhaps, first and foremost, is the evolution of computers and now AI. When I first started in the business, all records, both as far as insurers and their claims vs. premium from their brokers, as well as policy issuance and other similar items, were all done on a manual basis. This caused extreme delays as well as significant mistakes due to either carelessness or improper information. Today, with computers, the internet and now, AI, information flows much more quickly, material is stored in a much more professional manner, and policy information, as well as copies to insureds is prompt and efficient. AI is helping to create better data, storage, as well as more information on a live time basis.
This significant change has also made clients smarter as they can gather much information via AI, and therefore challenge their broker, which keeps the broker on their toes and keeps for a continued learning experience for both broker and client. By the client acquiring information that was not easily accessible years ago, the client has more questions, and the broker’s job becomes more creative.
What are the most important coverages in today’s world as compared to 20/30 years ago?
Coverages that have evolved over a similar period of time are Cyber Liability, and the extension of Directors & Officers Liability, both of which have grown in coverage as well as the number of insurer participations, which grant a higher limit. A fairly new coverage is Employment Practices Liability which has evolved due to the most recent political events.
Today, most insureds put significant value on premiums and can get much more coverage through manuscript policies and the data that is made available, not only from the insureds, but received by the insurance companies from third party sources.
“The smarter brokerage firms and their sales staff are constantly in touch with their clients, updating information and in a way, using this to prevent possible liability claims while trying to maintain a personal relationship.”
What concepts did you put into place, personally, that you feel contribute to securing the best coverage for clients?
I personally believe that there is still a large premium for service. Brokerage firms and their sales staff still need to maintain a relationship with both corporate and personal insureds and remember that there is plenty of time during the year to maintain the interchange of information as well as to maintain the personal touch. Clients do not appreciate only hearing from their broker when coverage is ready for renewal or when it is time for billing. The smarter brokerage firms and their sales staff are constantly in touch with their clients, updating information and in a way, using this to prevent possible liability claims while trying to maintain a personal relationship.
Will you provide an example of a challenging placement where you had to be creative in securing coverage for a client, whether business or personal?
One of the more challenging placements over the years has been the development of coverage in Argentina of a large energy company. They have many facets of coverage as well as many different countries that they operate in, and this requires a constant flow of information between the client and the broker and the insured’s companies. In addition, Argentina has had several economic problems which have led to either variation of currency value or delayed payment. It is a constant battle which appears to be getting easier with the current local administration making sure that there are no endorsements restricting premium timing.
Since the merger in 2018 of Crystal & Company and Alliant, what would you say were the main differences in how each company worked, and what has changed to enjoy a good broker/client relationship?
The main difference between Alliant and Crystal is in the type of clientele that they both had at the time of the merger. Specifically, Financial Institutions and High-Net Worth Personal Lines were crucial for Alliant and their acquisition and what was crucial for Crystal was the number of additional offices that were maintained by Alliant plus the additional leverage that both sides achieved through the combination of their resources, as well as premium volume. Today, that is a continuing growth pattern which has stood well over the seven years of time and has only become more efficient and productive.